


Pain at the Pump, Itch at the Polls
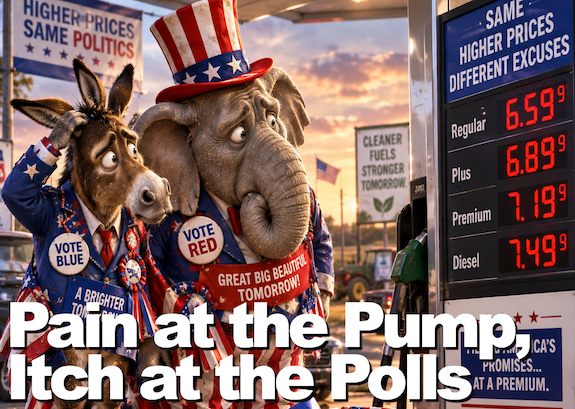
Six weeks before Election Day, the political clock is ticking, the diesel pump is running, and America’s bioeconomy is confronting an investment horizon measured in decades.
It’s 6:30 in the morning here in Digestville, and time to read the overnight news releases, scan the headlines, check the latest project announcements, and see what the world’s innovators have been up to while we were sleeping. There’s a new technology to investigate, a biorefinery moving toward commissioning, and a regulatory development that might change the economics of a billion-dollar project. The usual morning fare, and our 8:50 a.m. publishing deadline is approaching.
Ding. A text message. Ding-ding. Another one. An email arrives. Then another. The desktop lights up, the phone buzzes, and the inbox fills with urgent messages from people who apparently believe that the most important thing we can do this morning is stop reading about renewable fuels and start thinking about the November election.
Vote by mail! Request your ballot! Make your voice heard! One party wants our attention. The other party wants it, too. Apparently, the entire political world has discovered our telephone number.
We glance at the calendar. September 22. Six weeks until Election Day, and here in Florida, the statutory window for counties to begin mailing domestic vote-by-mail ballots opens on Thursday, September 24. Two days from now.
Good heavens. The election is no longer something happening in November. It is something arriving in the mailbox this week.
Meanwhile, the political world is doing what the political world does best: counting votes, counting districts, counting the days. The pollsters have their percentages, the mapmakers have their congressional boundaries, and the historians have their six-year itch, their electoral waves, and their cautionary tales of elections that did not turn out quite as expected.
But here at the Digest, we have another set of numbers on our minds: the numbers on the diesel pump. Somewhere in the American heartland, a farmer is getting ready for the day’s work. There’s a combine to fuel, a tractor to run, a truck to send down the highway. The pump clicks, the dollars climb, and the farmer watches the meter with the particular concentration of someone who knows that every gallon is coming directly out of the year’s operating margin.
Those numbers are not hypothetical. They are not a poll, a projection, or a statistical margin of error. They are the cost of keeping the farm running, and the bill comes due whether the farmer likes the government, dislikes the government, or would prefer to spend the morning thinking about something other than Washington. And here is where the election story becomes a bioeconomy story. The same agricultural economy that consumes enormous quantities of diesel also supplies the corn, soybeans, animal fats, agricultural residues, and other materials from which America makes renewable fuels. The farmer is both a customer of the fuel industry and a supplier to it. The biorefinery is both a manufacturing plant and a market for agricultural production.
And the policies governing the relationship between them are being debated in the middle of an energy-price shock, with an election approaching and billions of dollars in existing and proposed industrial investments hanging in the balance.
The political world is watching the polls. We’re going to watch the pump, the farm, and the biorefinery. Because whatever happens on Election Day, those three will still be there on November 4.
The six-year itch meets the diesel pump
Political historians have a name for one of the recurring phenomena of American electoral life: the six-year itch. It describes the tendency of the president’s party to lose congressional seats in the midterm election six years after first taking office. The pattern is familiar, though circumstances in 2026 are unusual given Donald Trump’s nonconsecutive terms.
We shall resist the temptation to turn historical averages into an election-night prediction. But the historical pattern raises a useful question for the bioeconomy: what happens when an election-year debate about economic performance coincides with a sharp increase in the price of one of the economy’s most important industrial fuels?
Diesel prices have surged past $6 per gallon nationally amid a global shortage, tight inventories, heavy refinery utilization and disruptions associated with conflicts in Iran and Ukraine. Reuters reported that U.S. diesel prices had risen 76 percent over the previous year and that diesel accounted for $51 billion of the $112 billion in additional spending at U.S. fuel stations during the Iran conflict. For the average motorist, gasoline prices are an immediate measure of the cost of living. For farmers, truckers, construction companies, and industrial operators, diesel prices are not merely a measure of household inflation. They are a direct charge against the cost of doing business.
The crop must be harvested. The grain must be delivered. The supermarket must be supplied. Heavy equipment does not become more fuel-efficient merely because the price at the pump has skyrocketed. Diesel is an input into the cost of producing and moving almost everything else, and unlike the price of an obscure commodity traded in distant futures markets, the price of diesel is displayed in giant illuminated numbers beside the highway.
You don’t need a PhD in economics to feel the sting.
The arithmetic of a bad harvest season
Consider a farming operation consuming 10,000 gallons of diesel during the harvest period. A $2-per-gallon increase in the fuel price adds $20,000 straight to operating expenses. For a larger operation consuming 50,000 gallons, the same increase adds $100,000.
Those are illustrations rather than estimates of the average American farm. Fuel consumption varies enormously by crop, acreage, equipment, irrigation requirements, transport distance, and when fuel was purchased.
The arithmetic, however, is mercilessly simple. When crop prices are determined in commodity markets, rising operating costs compress margins unless something else moves in the farmer’s favor. The same math applies to the truck carrying grain to market, the fleet moving biomass to a conversion facility, and the distribution network delivering finished fuel to customers. Which brings us to one of the more curious dualities of the American bioeconomy: a farmer can be hurt by rising fuel costs and benefit from stronger biofuel demand at the same time. A soybean grower may wince at diesel expenses while benefiting from demand for soybean oil used in renewable diesel or biodiesel. A corn grower faces higher field costs while also supplying the ethanol market.
There is no single national answer to whether the net effect is positive or negative. But there is an undeniable industrial reality: agriculture supplies both raw materials and customers to America’s renewable fuels industry. When petroleum prices spike, that relationship moves from the background to center stage.
The alternative fuel question: Can the bioeconomy help?
Whenever petroleum prices surge, interest in alternative fuels tends to rise with them. The logic is understandable: a country that produces more of its transportation energy from domestic agricultural and industrial resources has more options when petroleum markets become constrained or expensive.
But alternative fuels are not magic wands, and additional production capacity cannot be summoned into existence overnight to stop an immediate price shock. Ethanol is already blended into most American gasoline, but you can’t pour E85 into a conventional Class 8 diesel truck. Biodiesel can be blended into petroleum diesel within applicable fuel specifications and equipment requirements. Renewable diesel, when produced to the appropriate specifications, is a drop-in hydrocarbon fuel compatible with existing diesel applications. SAF addresses aviation.
A renewable diesel facility that is already operating may be able to raise output within the limits of its feedstock supply, equipment and contracts. But a project that has not yet reached Final Investment Decision cannot deliver a single extra gallon next week, no matter how attractive fuel prices become. That brings us to the policies that help determine whether those future plants ever get built.
The Renewable Fuel Standard: A market built by policy
The Renewable Fuel Standard has been a central pillar of American biofuel policy for nearly two decades. Administered by EPA, it requires specified renewable fuel volumes in the transportation pool and uses Renewable Identification Numbers, or RINs, as compliance credits.
Those credits have real economic value. They influence revenues available to biofuel producers and compliance costs borne by refiners. And that is where the long-running fight over Small Refinery Exemptions enters the picture. Refiners seeking exemptions argue that RFS compliance can impose disproportionate economic burdens on particular small facilities. Biofuel producers and agricultural organizations argue that exemptions can weaken renewable fuel demand and reduce the value and certainty of the market created by the mandate.
On August 31, EPA decided 34 petitions for the 2025 compliance year. It granted full exemptions to 18, partial exemptions to 11, denied three and found two ineligible. EPA said the decisions exempt 1.76 billion RINs across 29 small refineries, while also stating that it plans to propose reallocation of 100 percent of the gap between projected and actual exempted volumes into the 2026 and 2027 Renewable Volume Obligations.
That last part matters. The commercial consequence is not simply “1.76 billion RINs disappear.” It depends on how the reallocation is ultimately implemented, how markets respond, and what happens to actual renewable fuel demand and RIN values. For the farmer supplying oilseeds, the refinery managing compliance, the producer selling renewable fuel, and the investor deciding whether to fund another processing train, these administrative decisions can carry very different consequences.
The 45Z question: How long is a long-term investment?
Then there is the Clean Fuel Production Credit, better known as 45Z.
For fuel produced after December 31, 2025, the revised statute provides an applicable amount of either $0.20 or $1.00 per gallon or gallon-equivalent, depending on qualifying conditions, before the applicable inflation adjustment. The actual credit is calculated by multiplying that applicable amount by the fuel’s emissions factor and depends on satisfying the relevant statutory and regulatory requirements. The former SAF-specific $0.35 and $1.75 applicable amounts no longer apply to fuel produced after the end of 2025. That is the tax-policy detail.
But here is the project-finance problem campaign slogans usually leave out: Time.
A large biorefinery can take years to develop, permit, finance, construct and commission. Investors may expect the asset to operate for decades. Now imagine a developer asking a bank syndicate to finance a $500 million plant whose financial model depends materially on tax provisions, carbon-intensity scoring, regulatory interpretations and feedstock rules that may change materially during the project’s development or operating life.
That does not automatically make the project unfinanceable. It does, however, change the price of uncertainty. A lender may require additional equity, contractual protection, larger contingencies, stronger offtake arrangements or higher returns. A developer may postpone Final Investment Decision until more of the rulebook is visible. The electoral clock is always grinding, but the bioeconomy clock it governs — well, it sputters and starts every time a regulator in Washington gets a bad cold.
The dummymander: When optimization meets uncertainty
Which brings us, unexpectedly, to congressional redistricting.
A dummymander describes a map designed to improve a party’s electoral position that can perform differently when voting conditions move outside the assumptions under which the districts were constructed. One way this can happen is by spreading a party’s voters across a larger number of districts with narrower margins rather than concentrating them in fewer very safe seats.
Under the conditions the mapmaker expected, the arrangement may perform efficiently. Under sufficiently different conditions, several nominal advantages can weaken at once. For Digest readers, there is a familiar systems problem hiding inside that political term.
In industrial engineering and project finance, we encounter a related problem. A biorefinery designed around a particular feedstock price, tax credit, or regulatory framework may perform beautifully under its original assumptions, only to discover that the margins available to absorb an adverse change are uncomfortably narrow.
The facility may still be technically sound. Its chemistry may work perfectly. Its equipment may perform exactly as specified. But the financial model has run out of room. There is a common lesson here about the difference between optimization and resilience. A system designed to perform well under one set of conditions may prove less resilient when those conditions change. Political maps can eventually be redrawn. Industrial plants cannot redraw their debt covenants every time the regulatory wind changes direction. And that is where the short clock of politics begins to collide with the long clock of industrial capital.
The long clock and the short clock
Here, at last, is the central dilemma.
The political system operates on an electoral calendar measured in weeks, news cycles and congressional terms. The bioeconomy operates on an industrial calendar measured in development schedules, construction periods, harvest cycles, equipment lives, debt maturities and decades of expected operation. A fuel-price shock can arrive in days, yet a new production facility may take years, exposed to tax-rule variations, feedstock infrastructure development constraints, economic conditions that swirl like flurries in the Wyoming winds. Policy stability cannot mean policy immobility, yet long-lived industrial investments require enough clarity about rules, incentives and obligations for developers and investors to price the risks they are taking.
That distinction matters. Today’s plant is in today’s market, a SAF project still awaiting FID is responding to assumptions about markets and policy years from now. A farmer pays this week’s diesel bill now. A lender models cash flows through 2045. The clocks are all running — none of them at the same speed.
Back in Digestville
It’s getting close to 8:50 here in Digestville, and the morning’s publishing rush is nearly over. The technology announcements have been analyzed, the project pipelines updated, and the day’s bioeconomy news is almost ready to go.
The phone buzzes again. Another election message. And another. And another.
Here at The Digest, we’ll continue tracking the technologies, projects, markets and policies that shape the bioeconomy. We will run the numbers, interrogate the chemistry, and examine the real-world economics facing the people who build and operate America’s energy infrastructure.
Meanwhile, out in the heartland, the farmer has finished fueling the combine and pulled into the first rows of corn. The truck is rolling toward the elevator. The biorefinery is preparing for another day of production. The election will arrive on schedule. The harvest cannot wait. And the investment decisions that determine what fuels America will be producing ten or twenty years from now will matter long after the last campaign text message has been deleted from our phones.
The political world has six weeks to count the votes. The farmer has a fuel bill to pay today. And the bioeconomy has a much longer job to do.
Category: Top Stories

